What Is Personal Liability Coverage?
Personal liability coverage offers financial protection when you are legally responsible for another person’s injury or property damage. It can happen on your property or their property.
The key difference between personal liability and coverage for your house or belongings is that personal liability is considered third-party coverage. In other words, it covers injuries to others or damage to other people’s property, not you or your property.
Personal liability can cover medical bills, lost wages, legal fees, court-ordered judgments and settlements, and costs to repair or replace damaged property caused by you or a family member who lives in your household.
Real-World Examples of When Personal Liability Coverage Applies
Slips and Falls
Suppose a delivery driver slips on a patch of ice that hadn’t been salted, or a guest at your holiday party trips over the edge of a rug. If you’re found legally responsible due to negligence – you didn’t take steps to address the issue – personal liability coverage may apply if someone files a claim.
Dog Bites
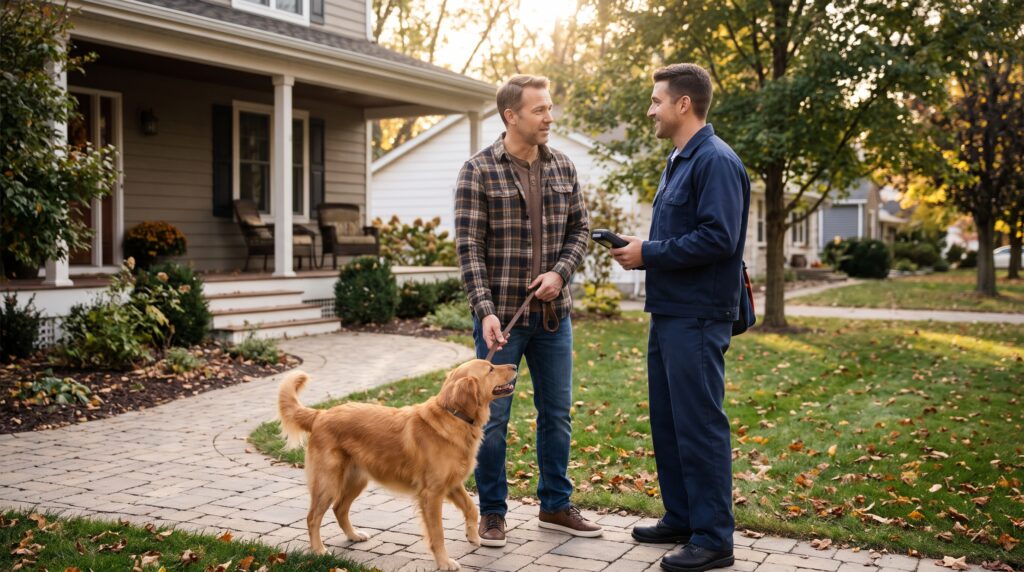
The family dog is happy to see a visiting friend but inadvertently knocks them down, or the dog bites an unfamiliar person. In this case, personal liability could help with a claim.
Damage to Someone Else’s Property
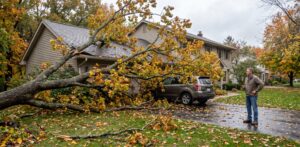
The baseball game in the backyard ends when your child throws a ball through the window of a neighbor’s house. A major storm sends a giant branch from the tree in your backyard through the roof of your neighbor’s house. You visit a friend’s home or a retail store and accidentally break a crystal vase. Depending on your policy terms, personal liability may cover some of the damage.
Common Exclusions
Personal liability doesn’t cover every accident. For example, intentionally trying to injure someone or cause damage, business-related activities, auto-related accidents, and injuries to you are typically not covered by personal liability.
Review Your Personal Liability Coverage With Stanton Insurance Group
Has someone filed a claim about an injury or damage that occurred in your house or while you were visiting their property? Want to review your coverage to clarify what is and is not covered? Schedule an appointment with Stanton Insurance Group today.